You Own Three Rentals and One Umbrella Policy: Does It Actually Reach the Rentals?
Does your personal umbrella cover your rental houses? How Texas landlords line up DP-3 liability, required underlying limits, LLC ownership and umbrella coverage.
Does your personal umbrella cover your rental houses? How Texas landlords line up DP-3 liability, required underlying limits, LLC ownership and umbrella coverage.
A hard freeze can burst a pipe in a North Texas home. What homeowners insurance usually pays, when heat and vacancy rules apply, and how to prepare for a freeze.
Employee theft, forged checks and fake invoices are usually not covered by property, GL or cyber. What commercial crime insurance covers for a Texas business.
Starting an expedite business with a cargo van in Texas? How for-hire authority, federal filings, liability limits, cargo and new-venture underwriting work.
Roofing is a hard class to insure in Texas. How height limits, storm work, subcontractors, completed operations and workers' comp shape a roofer's coverage.
A claim was filed against your surety bond. What the indemnity agreement says you owe, how a bond claim moves and what to do the day the surety's letter arrives.
Is your gooseneck covered if hail hits it or it is stolen from the yard? How owned trailers are scheduled, valued and covered on a Texas hotshot policy.
Who pays when a city requires code upgrades after a fire or storm? How ordinance or law coverage works for Texas commercial buildings, in its three parts.
Why did your workers' comp renewal go up? How a Texas experience modification factor is built from your claims, who has one, and what moves the number.
A dog bites a guest or a neighbor. What Texas homeowners liability coverage pays, how breed exclusions and bite history change it, and when limits run short.
If a fire or storm makes your Texas home unlivable, additional living expense pays the extra costs. What it covers, how long it lasts and how to claim it.
Hosting a holiday party or serving drinks at your business? How host liquor and liquor liability coverage differ for Texas businesses, and what to check first.
A driver delivers to a fake receiver. Does cargo coverage pay? How voluntary parting and fraud exclusions work for Texas carriers heading into holiday freight.
A finished job can still bring a lawsuit. How completed operations coverage works for Texas contractors, what takes it away, and what to check before you switch.
Hiring a sub without a certificate can raise your GL and comp audit and leave you holding the claim. How Texas contractors vet subs before the first check.
A Texas owner-operator's first day after a truck wreck: who to notify, what evidence to keep, what not to sign, how FMCSA rules may apply and who pays what.
Landlord insurance pays for sudden covered losses, not wear and tear or pet damage. What a Texas policy covers after a tenant leaves and what the deposit handles.
Own a commercial building you lease to a tenant? Learn what lessor's risk only covers, what the tenant insures, and where it differs from a BOP in Texas.
A package stolen from your porch is usually smaller than your deductible. Who to claim from first, when a homeowners or renters claim makes sense, what to check.
Renting a cabin or guest house by the night can fall outside a homeowners or landlord policy. See the gaps Texas hosts should ask about before the first guest.
Renting a truck for your Texas business? Hired auto physical damage explained: what HNOA leaves out, rental counter waivers, and how to close the gap.
Are dash cams worth it on a five-truck fleet? What video settles after a crash, how underwriters read a camera program, and the footage questions to settle first.
Leaking diesel tank at your yard, farm or shop? Why general liability usually excludes pollution, what a storage tank policy covers, and the rules to confirm.
Truck physical damage usually pays the lower of your stated amount and actual cash value. How to set the number, when to update it, and the gaps to watch.
Occupational accident coverage has limits, caps and exclusions workers comp does not. What Texas owner-operators and small fleets should compare before choosing.
What the life insurance exam checks, how rate classes work, how tobacco and health history land, and what can improve your class before you apply in Texas.
What the loss damage waiver at a Texas rental counter actually buys, what your own auto policy already covers, and the gaps: loss of use, credit cards, trucks.
Chimneys, space heaters, pipes on outside walls: what to check before the first North Texas cold front, and how your homeowners policy treats each risk.
When a neighbor's tree lands on your fence in Texas, your own homeowners policy usually responds first. How negligence, deductibles and debris removal work.
Insurance generally follows the car in Texas. What permissive use means, when a borrower's own policy helps, and when lending your car can cost you money.
Commercial auto, general liability, inland marine for the machine, and the MSA wording oilfield work demands: how to insure a Texas mobile welding rig.
Income multiples, the DIME method, and what to subtract: how a Texas family puts a real number on life insurance coverage before talking to a carrier.
The small number beside each coverage on a business auto policy decides which vehicles it applies to. Symbols 1, 2, 7, 8 and 9 explained for Texas businesses.
A renters policy does not protect your building, but it protects you in other ways. What a lease requirement does for a Texas landlord and how to track proof.
After you buy a home, offers for mortgage protection insurance show up in the mail. How it differs from term life, who gets paid, and how to size coverage.
When a cooler, compressor or AC unit quits, most property policies say no. How equipment breakdown and spoilage coverage work for Texas small businesses.
A stock tank or pond on your acreage raises real liability questions. How a Texas homeowners policy treats visitors, fishing guests, docks and bank damage.
Hundreds of strangers walk up to your door on October 31. What Texas homeowners liability covers for trick-or-treaters, and where pets and home haunts differ.
A lapsed policy can lead a mortgage servicer to buy coverage and bill you. What force-placed insurance is, the notices you should get, and how to end it.
A new MC authority stays pending until your insurer files with FMCSA. What the BMC-91X filing is, who sends it, the 20-day window, and what to have ready first.
Your car was repaired, but a wreck on its history cuts its resale value. How diminished value claims generally work in Texas and who they are made against.
Group life insurance through an employer usually ends the day you leave the job, often pays just a year or two of salary, and rarely is portable. Know the gap.
IRP registration and the 26,001-pound CDL line are different rules with different triggers. Here's when a Texas hotshot rig actually needs apportioned plates.
Comprehensive already covers a cracked windshield in Texas, but only full glass coverage waives the deductible. Here's the add-on to ask your agent for by name.
A leased-on hotshot relies on the carrier's policy while dispatched. Running your own MC authority means your policy carries it all. What changes when you switch.
A tractor or baler used for hay is usually excluded from a standard homeowners policy. What Wise County landowners need to add before this fall's second cutting.
Comprehensive coverage, not liability, pays for a break-in, hail ding, or hit-and-run in a Fair Park lot. What DFW drivers should check before the State Fair.
Fair rental value on a Texas DP-3 pays lost rent when a covered peril makes a rental unit uninhabitable, never when a tenant simply stops paying rent.
The 26,001-pound CDL line is identical in Texas and Oklahoma, but MC authority, cargo limits, and bobtail territory may not follow the truck across state lines.
A carport or add-a-room on a manufactured home can shift classification and TWIA eligibility. What to report to your Texas carrier, and when to do it.
A lender will not fund without homeowners coverage in force on closing day. What to have ready so a new build's insurance timing does not delay closing.
What liability-only really means on a Texas truck: how physical damage coverage works, what ACV pays on an older tractor, and when the gamble stops paying.
Hauling a non-runner in Texas changes the insurance picture. See how winch-loading, pre-existing damage, and theft on an idle trailer get handled differently.
A standard homeowners policy and flood insurance both exclude water that backs up through a sewer or drain. Here's what water backup coverage actually pays for.
Fire protection distance, water supply, outbuildings, replacement cost, flood zones and vacant-lot liability all change how acreage rates in North Texas.
PIP pays medical bills and lost wages after any accident; MedPay pays medical bills only. Why Texas makes you reject PIP in writing, and which fits your family.
Hit a deer in Texas? Why comprehensive pays instead of collision, what happens if you swerve and miss, and how Wise County drivers prep for deer season.
Builders risk during construction, the switch to homeowners at closing, and coverage after move-in: what changes at each stage of a North Texas custom home build.
How long accidents and tickets raise Texas car insurance rates, the three-to-five-year surcharge window, what CLUE shows carriers, and how the reset works.
Most small businesses assume cyber insurance is for bigger companies. Here's what actually triggers a claim, and why general liability doesn't cover it.
A paid-off Texas rental still needs its own DP-3 policy. See what changes once no lender sets the minimum, and what a free-and-clear owner has to track alone.
Key person life insurance protects a Texas business from the financial shock of losing a critical owner or employee, and it's not the same as a buy-sell policy.
Own more than one Texas rental? Here's how DP-1, DP-2 and DP-3 differ, why a schedule beats seven separate policies, and what a statement of values should show.
An older manufactured home isn't automatically uninsurable in Wise County. Why carriers screen by age, not condition, and what a specialty market wants to see.
GVWR, GCWR, and actual scaled weight aren't the same number. See how Texas hotshot haulers read the certification plate to know their real CDL and FMCSA status.
A park model built to ANSI A119.5 fails TDI's building code, so no WPI-8 is possible and TWIA closes on the dwelling. See what qualifies, and what to do instead.
Business income coverage replaces lost profit and expenses after a covered loss shuts a Texas business down. Here's what the limit and waiting period mean.
Your homeowners policy was not written for the business in your spare bedroom or kitchen. Here is where the coverage stops and what Texas owners add instead.
A general contractor wants five million in liability and your policy is nowhere close. Here is how small Texas contractors stack coverage to meet the number.
One line on your trucking declarations page says how far your trucks go. Here is what happens when the loads you take run past the radius you are rated for.
Pulling a trailer you do not own in Texas? Trailer interchange and non-owned trailer coverage are not the same. Learn which one pays for trailer damage.
Tiny homes and park models fall between homeowners, RV, and mobile home policies in Texas. Here is how coverage really works and what to ask before you buy.
Your disability policy pays you, not your practice. Learn how business overhead expense coverage pays the rent, payroll and leases while an owner is out.
Totaled car in Texas? Learn how insurers calculate actual cash value, where the valuation report goes wrong, and how to dispute a low settlement offer on your car.
Commercial carriers will not quote without loss runs. Learn what they show, how many years to request, and how to get them from your carrier yourself.
Some Texas agencies add a fee on top of your premium. Learn what state law requires, how to spot it on a quote, and why TAP Insurance Agency never charges one.
Turned down by two Texas auto insurers? TAIPA is the state's assigned-risk plan. Learn who qualifies, what it covers, and how to get back to a normal policy.
Does your hotshot rig need a CDL in Texas? Learn how the 26,001-pound combination rating works, why empty weight is irrelevant, and what it costs you.
When an employee drives their own car for work, your business can still be sued after a wreck. Here is how hired and non-owned auto coverage closes that gap.
Naming an ex-spouse or a minor as beneficiary can tie up a Texas family's life insurance payout for months. Learn the common mistakes and how to fix them.
A waiver of subrogation shows up in most Texas commercial contracts. Here's what it means, what it costs, which policies it touches, and how to get it added.
Hiring your first driver and buying a second truck change how your trucking insurance gets underwritten. Here is what to line up before you sign for either.
Own-occupation and any-occupation disability policies pay very differently after an injury. Here is what each definition means for Texas workers and business owners.
Hauling cars in Texas? Learn why cargo coverage on an auto transporter works differently, what limits brokers require, and the gaps that leave you paying.
The Texas Supreme Court ruled a tornado is a windstorm, so the higher wind and hail deductible applies. What North Texas homeowners should check today.
A hunting truck, project car, or spare pickup sits parked most of the year. See how Texas comprehensive-only storage coverage and low-mileage options work.
A hurricane makes landfall on the Texas coast, and 300 miles inland, DFW gets flash flooding, days-long outages, and damage most policies handle differently.
Football season means concession stands, fundraisers, and bounce houses. What North Texas booster clubs and volunteer groups should know about event liability.
A plain-language walkthrough of how a Texas defensive driving course actually works: who qualifies, how to ask the court, provider rules, and the deadlines.
Rebuilt-title cars cost less to buy and more to insure. How Texas carriers view salvage history, what coverage actually looks like, and what to expect on value.
Food trucks and concession trailers mix auto, liability, and property risk in one rig. Here is the coverage Texas vendors need before festival season starts.
What a Texas lawn care or landscaping business needs on the policy: general liability, commercial auto, equipment coverage, and workers' comp explained plainly.
Group long-term disability typically pays about 60% of base salary, often capped and taxed. Here is how Texas workers find the real gap and how to close it.
No paycheck does not mean no financial value. Here is how Texas families price out what a stay-at-home parent's daily work would cost to replace, and cover it.
Texas tow operators carry cars that aren't theirs, on the hook and in the yard. What on-hook and garagekeepers coverage do, and the gaps that end businesses.
Selling, inheriting, or renovating a vacant Texas home? Vacancy clauses can cut off vandalism and water coverage after 30 to 60 days empty. Here is what changes.
North Texas clay soil moves in dry summers, and foundations move with it. Here's what a Texas homeowners policy covers, what it excludes, and when to call.
Your truck is in the shop and the note is still due. How downtime and rental reimbursement coverage works for Texas owner-operators, and when it is worth buying.
The HUD tag, data plate, and foundation paperwork decide whether a Texas manufactured or mobile home can be insured. Here is what underwriters check first.
Non-renewed over hail in North Texas? The Texas FAIR Plan is the state's last-resort home insurance. What it covers, what it doesn't, and what changes Sept. 1.
Dove season opens September 1 in Texas. See how your homeowners, auto, ATV, and umbrella policies handle guns, gear, guests, and the lease before opening day.
Suspended license in Texas? Learn how an occupational driver's license works, the SR-22 filing the court requires, and how TAP Insurance files it fast.
A Wall Street Journal analysis found the five largest home insurers closed 44% of claims unpaid last year. Here's how accurate policy details protect you.
Texas HB 2067 requires insurers to automatically explain a declined, cancelled or non-renewed home or auto policy. Here is how to actually use that letter.
A standard RV policy assumes you have a house somewhere else. What full-timer coverage adds when the rig is your only address in Texas, and why it matters.
Fresh CDL, spotless record, and every quote comes back no. Here is the experience gap Texas underwriters are actually pricing, and the real path through it.
The MCS-90 protects the public, not you, and if your insurer pays under it you owe them back. What every Texas motor carrier should know before a claim.
An oilfield Master Service Agreement sets your insurance floor, not FMCSA. Additional insured, waiver of subrogation, and the gap that bites at claim time.
A broker will not dispatch you without a certificate of insurance. Here is what really delays a COI and how Texas truckers get one turned around fast.
Owner-operator programs cap near five trucks. Standard fleet markets want ten. Here is how North Texas fleets caught in the middle actually get covered.
Texas notary bond requirements explained — the $10,000 surety bond, how it differs from E&O insurance, and how to get bonded. Free quote from TAP Insurance.
Bought a Texas rental subject-to? Learn why servicers reject evidence forms, how to structure the policy so the name check clears, and what to have ready.
A straight look at final expense whole life insurance in Texas: the underwriting tiers, the two-year waiting period, and when term is the smarter buy.
General liability covers physical harm. It will not cover a mistake in your advice or your work. Here is how E&O fills the gap, and why the retro date matters.
¿Su seguro de casa paga un techo nuevo o un techo depreciado? Le explicamos RCV vs. ACV en español y cómo TAP lo pasa a Valor de Reemplazo. Cotización gratis.
Dump truck insurance in Texas: the liability, physical damage and cargo coverage haulers really need, plus the gaps that bite. Call TAP Insurance Agency today.
Own acreage or a ranch near Weatherford, Aledo, or Springtown? Here's what Parker County landowners need in a home and farm/ranch policy. Call TAP today.
Leasing your Texas land for hunting? Learn what the recreational use statute does and doesn't cover, and how landowners protect themselves. Call (800) 666-2254.
Keep horses on your Texas property? Your homeowners policy likely excludes equine liability. Learn what coverage you actually need. Call (800) 666-2254.
A 2024 Supreme Court decision changed how insurance-funded buy-sell agreements affect estate tax. Here's what Texas business owners should ask their CPA and attorney.
Wondering if usage-based car insurance is worth it in Texas? See how telematics apps score DFW drivers, what you can really save, and when you should skip it.
Clean record but a higher car insurance bill? See what's driving DFW auto rate increases in 2026 — repair costs, hail, uninsured drivers — and how to push back.
Barns, shops, and fences fall under Other Structures coverage on a Texas homeowners policy. Learn what Coverage B pays for, common gaps, and how to fix them.
The good student discount can cut a Texas teen's auto premium 10 to 25 percent. Who qualifies, what documentation carriers want, and why families miss it.
Seven levers that actually lower what a teen driver costs on a Texas auto policy, from vehicle assignment and good student credits to shopping the household.
Five insurance moves Texas families miss every August: new drivers, dorm contents, carpool liability, student laptops, and college auto coverage.
Your auto liability usually follows the trailer. The damage to the trailer itself usually doesn't. Here's the gap Texas drivers find out about too late.
Texas doesn't require jet ski insurance, but your marina, lender, and lake rules might. What PWC coverage costs in Texas and what it actually pays for.
Wrecked in DFW? Here's exactly what to do after a car accident in Texas — the scene checklist, claim deadlines, and rate impact explained. Call (800) 666-2254.
Wise County burn ban in effect? See how Texas home and auto policies really respond to grass fire damage, which limits fall short, and how to close the gaps now.
Wondering if a speeding ticket raises your car insurance in Texas? Here's how moving violations affect DFW rates and smart ways to keep your premium down.
Your general liability policy won't replace stolen or storm-damaged tools. See how tools & equipment insurance protects Texas contractors. Call (800) 666-2254.
Sending a student to college in Texas this fall? Here's what changes on your auto policy, when they'll need renters insurance, and how to avoid overpaying.
Do Texas trade contractors need a license or permit bond? Learn what these bonds cover, what they cost, and how to get bonded fast for city and county permits.
105-degree days aren't just uncomfortable, they cause real home damage. Here's what Texas homeowners insurance does and doesn't cover during extreme heat.
How much motor truck cargo insurance do Texas owner-operators and fleets really need? Coverage limits by freight type, key exclusions, and broker requirements.
Heading to a Texas car show this summer? A standard auto policy won't protect a classic or antique car the way it should. Here's what real coverage looks like.
Roof age drives your Texas homeowners insurance rate, eligibility, and hail claim payout. See how DFW carriers view older roofs in 2026 and how to keep coverage.
Does your homeowners policy cover your ATV or UTV? Usually not. Here is what Texas ranch and recreational owners actually need for real ATV or UTV coverage.
Your DFW commute quietly shapes your car insurance rate. Learn how mileage, usage, and ZIP code affect your premium, and how TAP Insurance Agency helps you save.
Standard commercial property policies exclude flood damage entirely. Here's how NFIP and private flood insurance actually work for Texas small businesses.
Just married in North Texas? TAP Insurance Agency shares 6 smart insurance moves for newlyweds: combine auto, bundle home, and save. Call or text (800) 666-2254.
Wind, hail, and flood damage are covered by three different things in Texas. Here's a clear breakdown of which policy pays for what before the next storm hits.
Can't buy or increase home insurance once a hurricane forms? Here's why insurers freeze new coverage — and what inland North Texas homeowners should do now.
A duplex or fourplex isn't a bigger single-family rental — it's a different insurance conversation. Here's what Texas owners of 2-4 unit properties need.
Underinsuring your Texas business property can shrink your claim check even on a partial loss. Here's exactly how the coinsurance clause works, with real math.
Two Texas homeowners, identical hail damage, two different claim checks. Here's exactly how ACV vs. replacement cost settles a roof claim, with real numbers.
Labeled a high-risk driver in Texas after tickets, an accident, or a DWI? Learn how high-risk auto insurance works, what it costs, and 6 practical ways to save.
How much does general liability insurance cost for a Texas small business in 2026? See real price ranges, what drives your premium, and how to keep it low.
Do Texas contractors need bonds on public projects? Learn how bid, performance, and payment bonds work, what they cost, and how to get bonded fast with TAP.
Most Texas cargo policies exclude reefer breakdown, so a failed unit can leave your spoiled load uncovered. Learn what the endorsement covers and how to add it.
From presses to DTF and UV printers, a Texas print shop needs more than basic coverage. See what BOP, property, and equipment breakdown insurance protect.
Full coverage or liability-only? See how the two compare, what each costs DFW drivers, and when to keep or drop full coverage. Ask TAP Insurance Agency.
New to Wise County, Texas? Use this simple move-in insurance checklist for your home, auto, and renters coverage. TAP Insurance Agency: (800) 666-2254.
Wondering how much an SR-22 costs in Texas in 2026? See the small filing fee, how a DWI or violation raises your premium, and smart ways to lower your rate.
An additional insured lets your Texas clients, GCs, and landlords share your liability coverage. Learn what it means, why it's required, and how to get one fast.
Getting a Texas dealer license? The TxDMV requires a $50,000 auto dealer surety bond. Learn what it costs, who needs one, and how to get bonded fast with TAP.
Motor truck cargo insurance protects the freight you haul. Learn Texas coverage limits, costs, exclusions, and the gaps owner-operators miss before a claim.
Renting out a Texas house? A homeowners policy will not cover it. Here is how DP-3 dwelling fire landlord insurance works and what yours should include.
Texas requires liability coverage on motorcycles too, but that rarely covers the cost of a real wreck. Here's what real motorcycle coverage should include.
Heading out in your RV this summer? Learn what Texas RV insurance covers, why your auto policy falls short, and how to protect your North Texas road trips.
Most carriers won't insure a manufactured or mobile home in Texas — we will. Here's what coverage you need, what it costs, and why an independent agent matters.
If your SR-22 lapses in Texas, your insurer files an SR-26 and your license can be suspended. Learn what a lapse really costs and how to keep coverage active.
A Business Owner's Policy bundles general liability and property coverage for Texas small businesses, often for less. See what a BOP covers and who needs one.
The FMCSA requires every Texas freight broker to carry a $75,000 BMC-84 surety bond. See what it covers, what it really costs, and how to get bonded fast.
Motor truck cargo insurance protects the freight you haul in Texas. Learn what it covers, what it excludes, and how much coverage owner-operators really need.
Driving for Uber, Lyft or DoorDash in DFW? Your personal auto policy may not cover you on the clock. Learn how Texas rideshare and delivery drivers close the gap.
Do you need boat insurance for Lake Bridgeport or Eagle Mountain Lake? TAP Insurance Agency breaks down Texas watercraft coverage, costs, and smart ways to save.
Need an SR-22 in Texas but don't own a vehicle? Learn how non-owner SR-22 insurance works, who needs it, and how to get it filed fast with TAP Insurance.
How to insure a brand-new home in Rhome, Decatur, Boyd, and across Wise County: builder's risk, your first policy, discounts, and what your lender will require.
Surety bonds and insurance protect different parties. Learn how they differ, when your Texas business needs each, and how TAP Insurance gets you bonded fast.
Need a surety bond in Texas? Learn what bonds cost, which ones your business needs, and a simple 5-step checklist to get bonded fast. Call (800) 666-2254.
Bobtail and non-trucking liability aren't the same coverage. TAP Insurance explains what each protects and why owner-operators need both. Call (800) 666-2254.
Five hidden gaps in North Texas homeowners policies — wind/hail deductibles, flood, water backup and more — and how to close them. TAP Insurance: (800) 666-2254.
Most DFW drivers overpay because they never ask. Here are 7 car insurance discounts North Texas drivers forget about, and how TAP Insurance finds them.
Heading into summer in Wise County? Review your wind and hail deductible, bundle home and auto, and cover your lake toys. Call TAP Insurance at (800) 666-2254.
An SR-22 in Texas usually lasts two years after reinstatement. How the clock works and how to stop overpaying for high-risk auto. Call (800) 666-2254.
General liability vs. commercial auto: what each one covers, where they overlap, and which your Texas small business actually needs. Call (800) 666-2254.
What does a surety bond cost in Texas? Most premiums run just 1-3% of the bond amount. See what drives your rate and how to pay less. Free quote: (800) 666-2254.
Your CSA score quietly drives up Texas trucking insurance rates. See what underwriters look for and how owner-operators can lower premiums. Call (800) 666-2254.
Builder's risk covers a structure while it is under construction: fire, wind, theft, and more. Who needs it in Texas and what a policy should include.
Nuclear verdicts hit a record median in 2024, and Texas is a hot spot for them. Here's how they drive truck insurance costs and what owner-operators can do.
Is your North Texas roof paid at ACV or RCV? How roof depreciation schedules and percentage hail deductibles can cost you thousands, and how to check.
Most DFW drivers overpay for car insurance. Seven discounts North Texas drivers forget to ask about, from bundling to telematics. Call (800) 666-2254.
Summer storm season is here in Wise County. Get your home and auto ready for hail and high wind, and see how bundling can save you. Call (800) 666-2254.
An SR-22 in Texas usually lasts two years. Learn how the filing works, how to avoid restarting the clock, and 4 ways to lower your high-risk auto rate.
Confused about term vs. whole life insurance in Texas? Compare cost, coverage length, and cash value so your family can pick the right policy with confidence.
Five signs your Texas small business needs commercial auto insurance — plus how general liability fits in. Get a free quote from TAP Insurance at (800) 666-2254.
Need a surety bond in Texas? Learn how DFW business owners get bonded fast in 2026 - bond types, costs, and three steps to quick approval. Call (800) 666-2254.
Your FMCSA CSA score affects what you pay for trucking insurance in Texas. Learn the 7 BASICs and how to lower your score. Call TAP Insurance at (800) 666-2254.
A North Texas hail roof claim can pay thousands less than a new roof costs. How RCV vs. ACV and wind/hail deductibles change your payout. (800) 666-2254.
Road trip season is here. See how DFW drivers can lower auto insurance with mileage discounts, bundling, and a quick coverage review. Free quote: (800) 666-2254.
Learn what commercial trucking insurance you need in Texas. Covers FMCSA liability, cargo, physical damage, and rate factors for owner-operators and small fleets.
A $1M umbrella policy can cost as little as $15 a month and protects DFW homeowners when a liability claim exceeds standard limits. See who really needs one.
What are surety bonds and who needs them in Texas? TAP Insurance helps contractors, auto dealers, and notaries get bonded fast online. Call (800) 666-2254.
Atlantic hurricane season runs June 1 through November 30. Here's what Texas homeowners, renters, and business owners should check before a storm hits.
Premium financing lets Texas businesses spread a large commercial premium over monthly payments. How it works, what it costs, and when it actually makes sense.
TAP Insurance Agency now offers Germania Insurance, a member-owned Texas mutual insurer since 1896. See what it means for your home, auto, and ranch coverage.
A backyard pool is one of the best parts of a Texas summer and a serious liability risk. Learn what your homeowners policy covers and where it leaves you exposed.
Bobtail and non-trucking liability sound alike but cover very different things. See what each one does for Texas owner-operators leased onto a motor carrier.
Juggling several commercial auto policies with different renewal dates? Learn how commercial fleet insurance works in Texas and when it is time to consolidate.
Motor truck cargo insurance covers the freight you haul against damage, theft, and loss. See what it covers, what it excludes, and how much Texas truckers need.
Texas auto insurance is expensive, but cutting coverage is not the answer. Here are 7 proven ways DFW drivers can lower premiums without reducing protection.
Wise County home and auto bundle in 2026 — why the math has changed, how independent agents save more, real numbers for Rhome, Decatur, Bridgeport, Boyd.
Texas box truck insurance for owner-operators, expediters, and small fleets in 2026. Coverage breakdown, cost ranges, and quote checklist. Call (800) 666-2254.
If your family depends on your income, term life insurance is the cheapest peace of mind you can buy. Here's the Mother's Day reminder to check your coverage.
Sola Insurance covers your wind/hail deductible up to $25,000 — paid in 3-5 days, no adjuster, no CLUE report. DFW homeowners save thousands during storm season.
Texas is the only state where private employers can opt out of workers comp. Here's why most small businesses still need coverage — and what happens if you don't.
60% of Texas drivers haven't compared auto rates in 3+ years. 2026 is the first year auto rates dropped in five — best time in half a decade to shop.
Standard Texas homeowners covers tornado wind damage but the deductible math, ALE limits, and personal property settlement matter. Read before storm season.
Independent insurance agencies shop 15+ carriers for you. Captive agents only sell one. Why it matters for Texas drivers and homeowners in 2026.
TAP Insurance Agency upgrades to HawkSoft AMS. Faster service, smarter renewals, better client tracking across Texas and Oklahoma.
A DUI or DWI in Texas means SR-22, higher rates, and possible non-renewal. TAP Insurance Agency walks through what to expect and how to find affordable coverage.
If your financed car is totaled, insurance pays actual cash value, not your loan balance. How gap insurance covers the difference for Texas drivers who finance.
General liability insurance protects Texas contractors from bodily injury and property damage claims. Learn what it covers, costs, and how to qualify for work.
Texas homeowners insurance premiums rising in 2026. Learn why rates are up 18-28% and 8 strategies to lower yours without sacrificing coverage.
Personal umbrella insurance protects your Texas assets when home/auto liability limits aren't enough. Learn why homeowners and business owners need it.
Texas renters insurance costs $15-25/month and covers your belongings, liability, and temporary housing. Learn what's covered and why every renter needs it.
A Texas DUI raises your auto insurance 60-80%. Learn how to find affordable coverage, when rates drop, SR-22 requirements, and strategies to save.
Learn what surety bonds are, which Texas businesses need them, how much they cost, and how to get bonded quickly. Guide from TAP Insurance Agency.
Not sure if your Texas property is in a flood zone? Here's exactly how to check your flood zone designation and what it means for your insurance requirements.
Learn what a Certificate of Insurance (COI) is, when Texas businesses need one, and how to get one fast from your independent agent.
Adding a teen driver in Texas can double or triple your auto insurance premium. Here's why—and the strategies that can actually help lower the cost.
Many Texas small businesses carry coverage limits set years ago that no longer reflect real exposure. Here's what underinsurance costs and how to fix it.
If your employees use personal vehicles for work, or you rent vehicles for business, hired and non-owned auto coverage could save your company from a lawsuit.
Many Texas homeowners discover their policy falls short when disaster strikes. Learn what replacement cost vs. actual cash value really means for your family.
Your homeowners insurance was cancelled or non-renewed in Texas. Find alternative carriers, understand your options, and protect your home today.
Texas is the only state that does not require workers' comp. Going without it can cost a business everything. Here is what Texas owners need to weigh first.
Texas auto insurance is up 60% since 2020, the largest jump in the nation. Here is what is behind it and what DFW drivers can do about rising premiums.
Closing on a Texas home soon? You'll need an insurance binder. Learn what it is, how to get one, and why your mortgage lender requires it before closing day.
Your credit score can triple your car insurance premium in Texas. How insurers use credit, what you can do about it, and how to find a better rate anyway.
Buying your first home in Texas? Avoid these 5 common insurance mistakes that cost new homeowners thousands. From skipping flood coverage to ignoring deductibles.
DFW homeowners are being dropped over hail risk. Why it is happening, what your options are, and how an independent agent can help you keep coverage in place.
Comprehensive auto insurance covers more than you think. From hail damage to theft to hitting a deer, here's what Texas drivers need to know about comp coverage.
Your Texas hail deductible can be $3K-$17K out of pocket. See how to cover it with a separate policy starting at ~$300/yr. Call (800) 666-2254.
Texas auto insurance rates are stabilizing in 2026 after years of steep increases. What is driving costs, how DFW drivers can save, and what to watch this year.
Progressive paused new homeowners policies in Texas. Learn why, which carriers are still writing, and how to find the right coverage for your home today.
Texas trucking insurance rates are up 5-10% in 2026. Learn what's driving increases and 5 proven strategies to lower your premium. Free quotes from TAP Insurance.
Texas leads the nation in flood claims. Learn flood risk, what homeowners insurance does NOT cover, NFIP options, and how to choose flood coverage in 2026.
Using a personal auto policy for work can get a claim denied. The difference between commercial and personal auto insurance, and which one Texas businesses need.
DFW homeowners: spring checklist to protect your home. Storm damage, hail, coverage updates, liability. Free policy review from TAP.
Learn what independent insurance agents do, how they differ from captive agents, and why choosing an independent agent can save you money.
What commercial insurance does your Texas business need? Learn about GL, BOP, workers comp, and more for small business owners.
New to buying a home in Texas? Learn what homeowners insurance covers, Texas-specific risks, and how to choose the right policy.
Learn which auto insurance coverage you really need in Texas. Understand liability limits, comprehensive, collision, UM/UIM, and more.
Independent agencies bundle insurance across multiple carriers for bigger savings. See how TAP Insurance rechecks your rates at every renewal.
Complete guide to UM/UIM coverage in Texas. Why you need it, how it works, limits, and Texas-specific rules.
Hotshot insurance in Texas runs about $500 to $1,000 a month for one truck. See non-CDL and new-authority costs, and what pushes your price up or down.
Local insurance guide for Wise County, TX including Rhome, Decatur, Bridgeport, Boyd. Auto, home, business insurance for truckers and families.
Complete insurance checklist for starting a trucking company in Texas. Coverage types, FMCSA requirements, and owner-operator tips.
Complete guide to FMCSA compliance requirements for trucking companies in Texas. DOT registration, MC numbers, insurance requirements, and more.
Texas leads the nation in hail damage claims. Learn when hail season hits DFW, what your insurance covers, and how to prepare your home and car.
Find out what trucking insurance costs in Texas for owner-operators, small fleets, and hotshot haulers. Get factors that affect your rates and tips to save.
Learn when you need SR-22 insurance in Texas, how much it costs, how to file, and how long you need it. Get affordable SR-22 quotes from TAP Insurance Agency.
Seven practical ways Texas drivers can lower auto insurance in 2026 without cutting coverage: discounts, deductibles, bundling, and shopping independently.
Wise County homeowners face hail, wind, and wildfire risk. Practical coverage tips for Rhome, Decatur, Boyd, Bridgeport, Alvord, and Paradise homeowners.
Five reasons an independent agent saves you money on auto, home, and business insurance in Rhome and Wise County, starting with shopping multiple carriers.
FMCSA will not activate your authority without the right filings. The insurance you need, the limits required, and how to avoid delays that cost you weeks.
New owner-operators: five insurance realities to understand before your first load - primary liability, physical damage, cargo, bobtail, and what it all costs.
Captive agents sell one company's policies; independent agents shop many. How that difference affects the price, coverage, and service you get here in Texas.
Texas leads the nation in hail claims. How the claims process works, what your policy pays, and the steps DFW homeowners should take before the next storm hits.
Texas is the only state that does not require workers' comp. What the coverage does, what non-subscribing really costs you, and how to decide for your business.
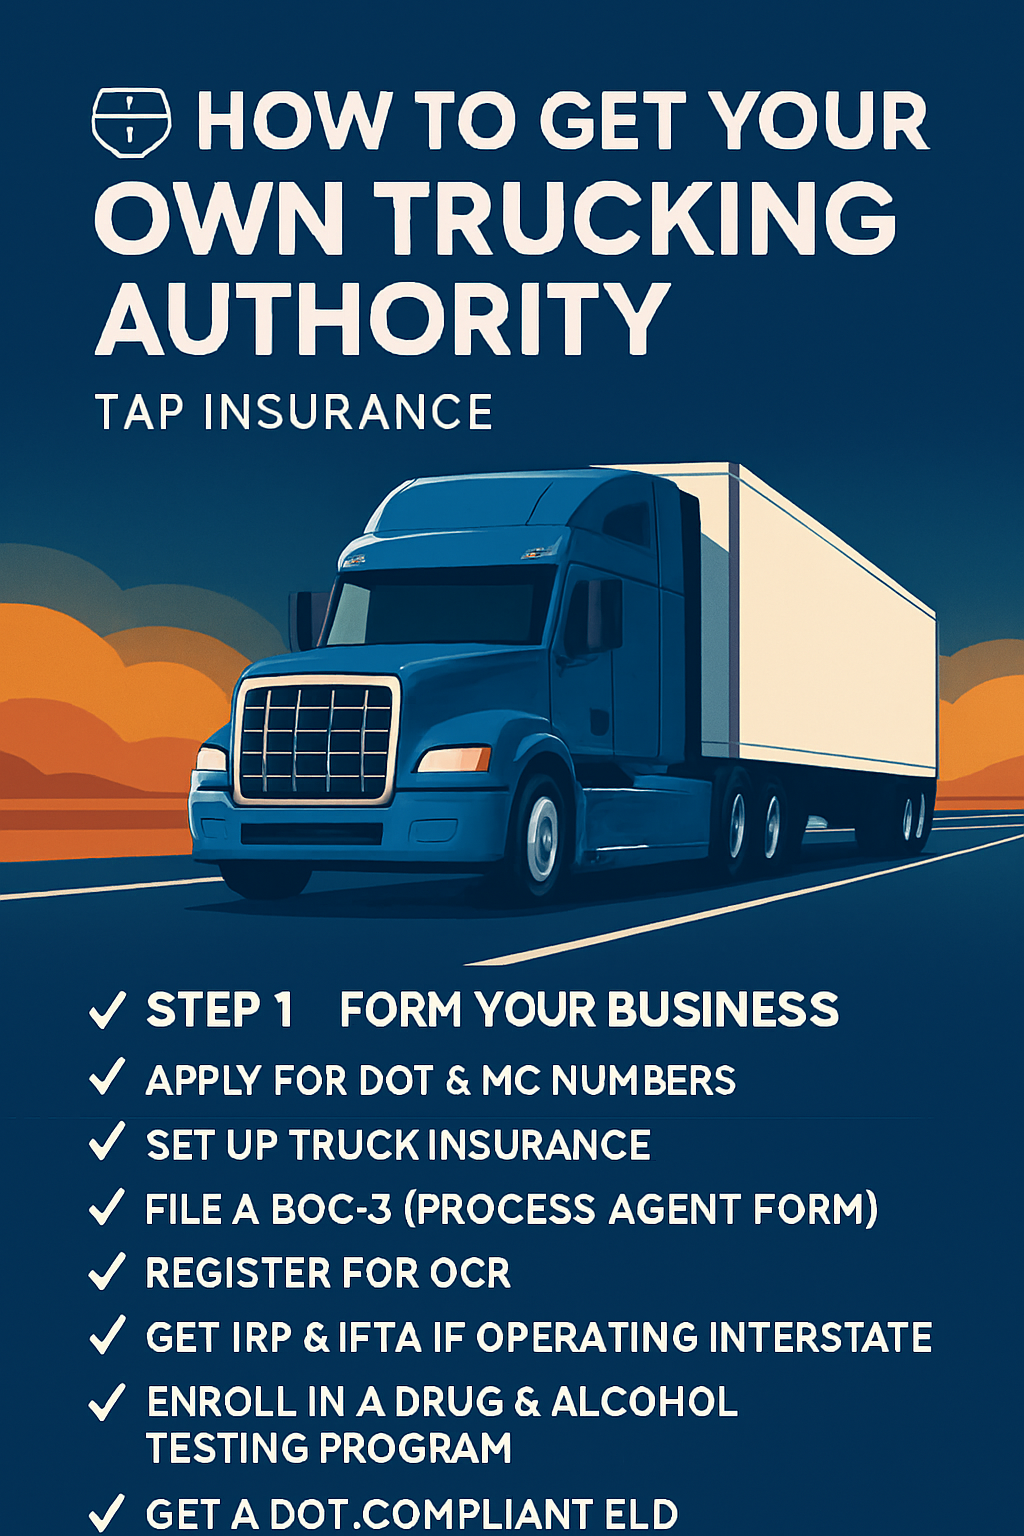
A step-by-step guide to getting your own trucking authority in Texas: forming the business, DOT and MC filings, BOC-3, UCR, and the insurance FMCSA requires.
How sharing your current policy details through Canopy Connect helps TAP Insurance Agency find you a better rate faster, securely and without the guesswork.