The First Hard Freeze Splits a Pipe in the Wall: What Texas Homeowners Insurance Pays
A burst pipe is usually a covered sudden loss, but the answer can change when the house was empty, the heat was off or the leak had been dripping for weeks.
Say a family in Wise County drives to Abilene for a long weekend in early winter. A cold front pushes the temperature into the teens on Saturday night, and a supply line inside an exterior wall splits. They come home Monday to water across the hardwood floors and a sagging ceiling below the bathroom, and the first question is whether homeowners insurance will pay for any of it.
Generally, yes, when the pipe burst suddenly and accidentally, most standard homeowners policies cover the resulting water damage to the house and often to belongings too. The answer can change if the home sat empty with the heat off, or if the water had been leaking slowly for weeks. Policies differ, so confirm the details with your agent before you count on a payment, and remember that this is general education, not legal advice about your particular claim.
Sudden water damage versus the slow leak
Many policies, including the common HO-3 homeowners form, cover sudden and accidental discharge of water from plumbing, and that often includes a pipe that splits from freezing. The word that matters is sudden. A line that cracks on a cold night and floods a wall in a few hours looks very different to an adjuster than a drip that has been soaking a cabinet for months.
Leaks that go on over a long stretch, often 14 days or more, are commonly treated as seepage and may be excluded, along with wear and tear and damage from poor maintenance. A drain that backs up is also a different animal, because water coming up through a drain generally is not part of the base policy at all. If you want to see how that works, read about water backup coverage, which is a separate add-on, before the next heavy storm.
What the policy usually pays after a burst pipe
When the loss qualifies, the policy generally pays to repair the damage the water caused: flooring, drywall, insulation, the ceiling below and often the contents that got soaked. Many policies do not pay to fix the failed pipe itself, though some will pay for the tear-out and access needed to reach it. What is included varies, so ask how your policy treats the plumbing repair versus the damage around it.
Mold is another place to read closely. Many policies limit what they pay for mold, even when it grows after a covered loss, and a deductible applies to the claim as well. Drying the house out quickly is one of the best ways to keep a bad loss from becoming a worse one. Ask your agent how your policy handles mold, and whether the limit is something you would want raised.
The heat clause and the empty house
Here is the part that surprises families on a long weekend. Many policies exclude freeze damage when the home is vacant or unoccupied unless you used reasonable care to keep the heat on, or shut off the water and drained the system. The wording differs, and a short trip is often treated differently than a home left empty for weeks.
It helps to understand what changes when a house sits empty, because the definitions of vacant and unoccupied can matter more than people expect. If you travel in winter, leaving the thermostat set to a safe temperature is generally the simplest way to show reasonable care. Check your own policy language or ask your agent how it handles an absence, especially if the family spends several nights away or a house sits empty between a sale and a move. A quick call before the trip is a small effort next to a floor that has to be torn out.
Why North Texas homes freeze differently
Many North Texas homes sit on slab foundations, and a lot of them were designed with summer heat in mind, not hard freezes. Supply lines often run through exterior walls and attics, where a few hours of single-digit wind chill can do real harm. A pipe that has never frozen in twenty years can still split on the one night the forecast is wrong.
February 2021 and Winter Storm Uri showed how widespread this can get. When thousands of homes break pipes at once, claims pile up, plumbers get booked out for days and drying crews run behind. That backlog is one more reason to stop the water fast and document everything while you wait for help. It also helps to keep a plumber's number handy and to ask your agent early what the claim process looks like when a lot of neighbors are filing at the same time.
What to do in the first hour
Shut off the main water valve first, and shut off the electricity to affected areas if water is near outlets and it is safe to do so. Then take photos and video of the damage before anything is moved. Your policy generally requires reasonable steps to prevent further damage, so stopping the water and starting to dry things out is part of the claim, not something that hurts it.
Call your agent or the claim line as soon as you can, and ask what the carrier wants you to do next. Keep receipts for emergency plumbing, fans, tarps and any temporary lodging, since many policies reimburse reasonable costs. Do not throw away damaged items until the adjuster has seen them or approved it. A simple room-by-room list of what was damaged, written while it is fresh, can save a lot of back and forth later.
Getting ready before the freeze warning
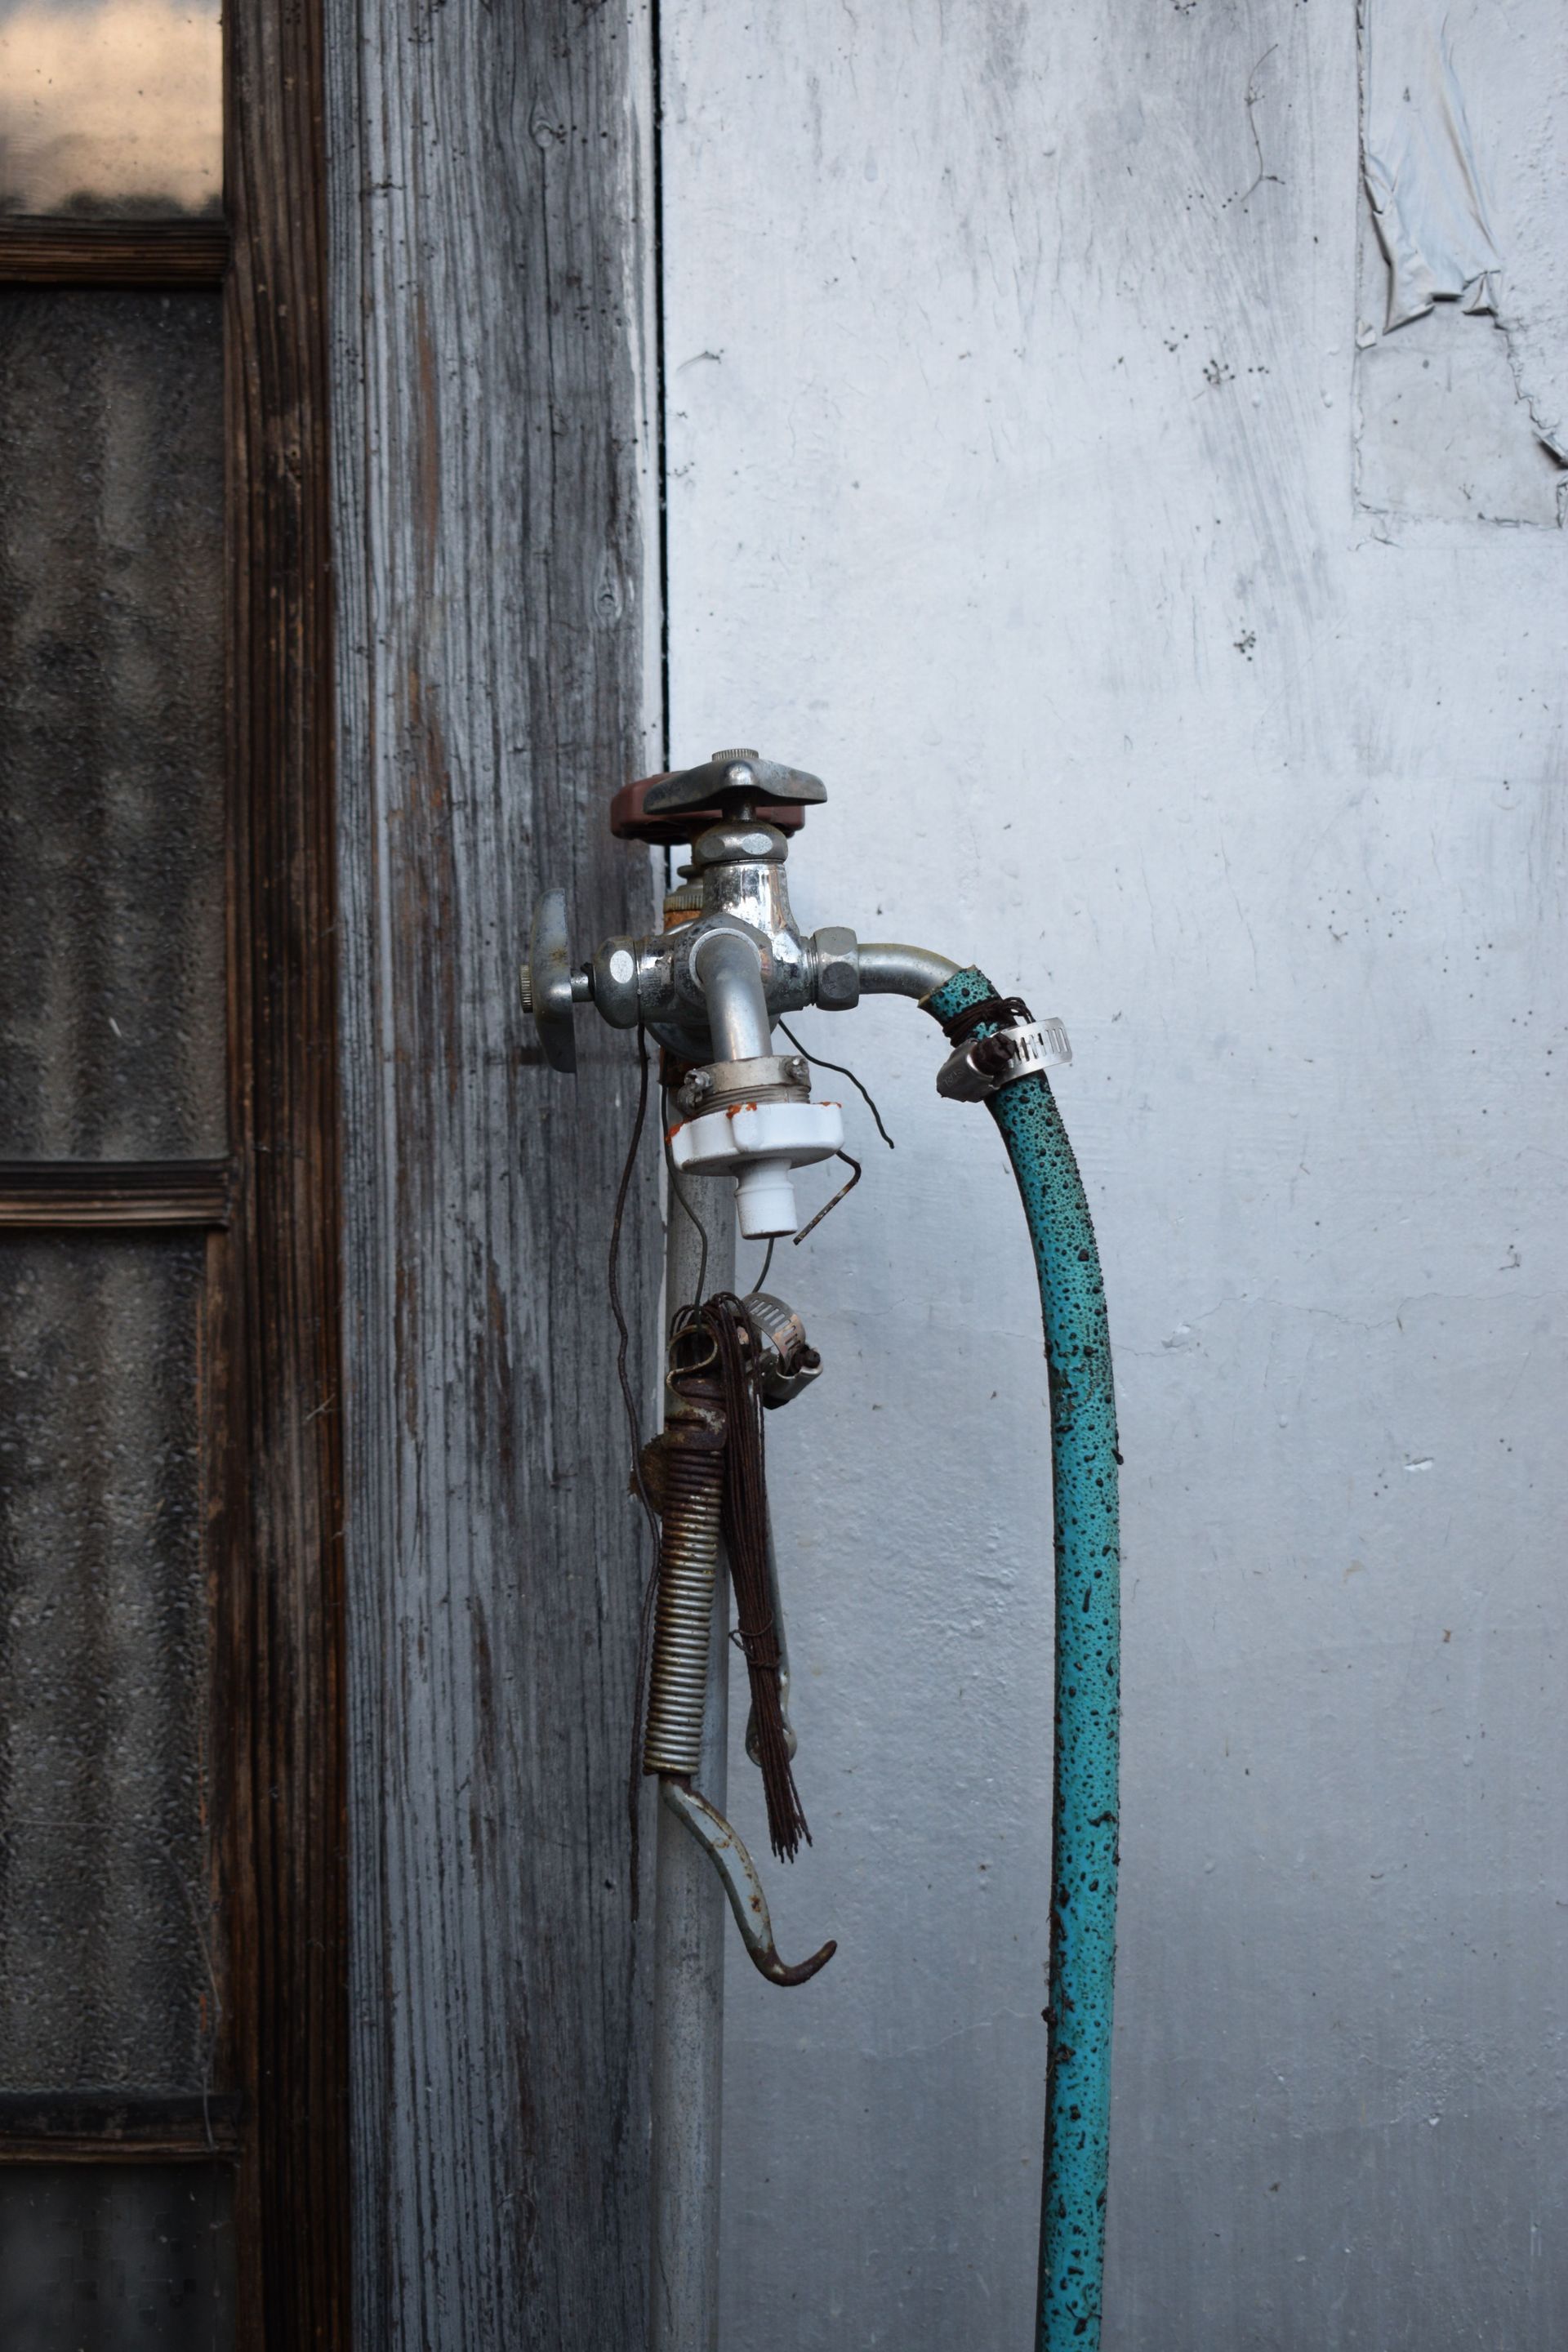
Protect the exposed pipes. Insulate lines in the attic, crawl spaces and exterior walls, and cover outdoor faucets. Letting faucets on exterior walls drip and opening the cabinet doors under sinks helps warm air reach the pipes.
Know your main shutoff. Every adult in the house should know where it is and how to turn it, and a labeled tag on the valve helps a guest or a sitter. In a bad freeze, seconds count.
Watch the house when you are away. Keep the thermostat on a safe setting, and consider a smart leak detector, which can text you when it senses water. Some carriers offer a discount for them, so it is worth asking.
Review your coverage in the fall. Ask about your freeze and vacancy conditions, your deductible and whether you want water backup added.
TAP Insurance Agency is an independent agency that shops multiple markets, so we can compare how different carriers word their freeze and vacancy rules before a cold snap tests them. When you are ready, you can get a home insurance quote and we will walk through the details together, in plain English.
— TAP Insurance Agency · Call (800) 666-2254 — or text QUOTE to (817) 646-6700 · tapinsuretx.com