Manufactured & Mobile Home Insurance in Texas
Manufactured & Mobile Home Insurance in Texas
Coverage for the homes most carriers turn away — written by an independent agent who actually has the markets.
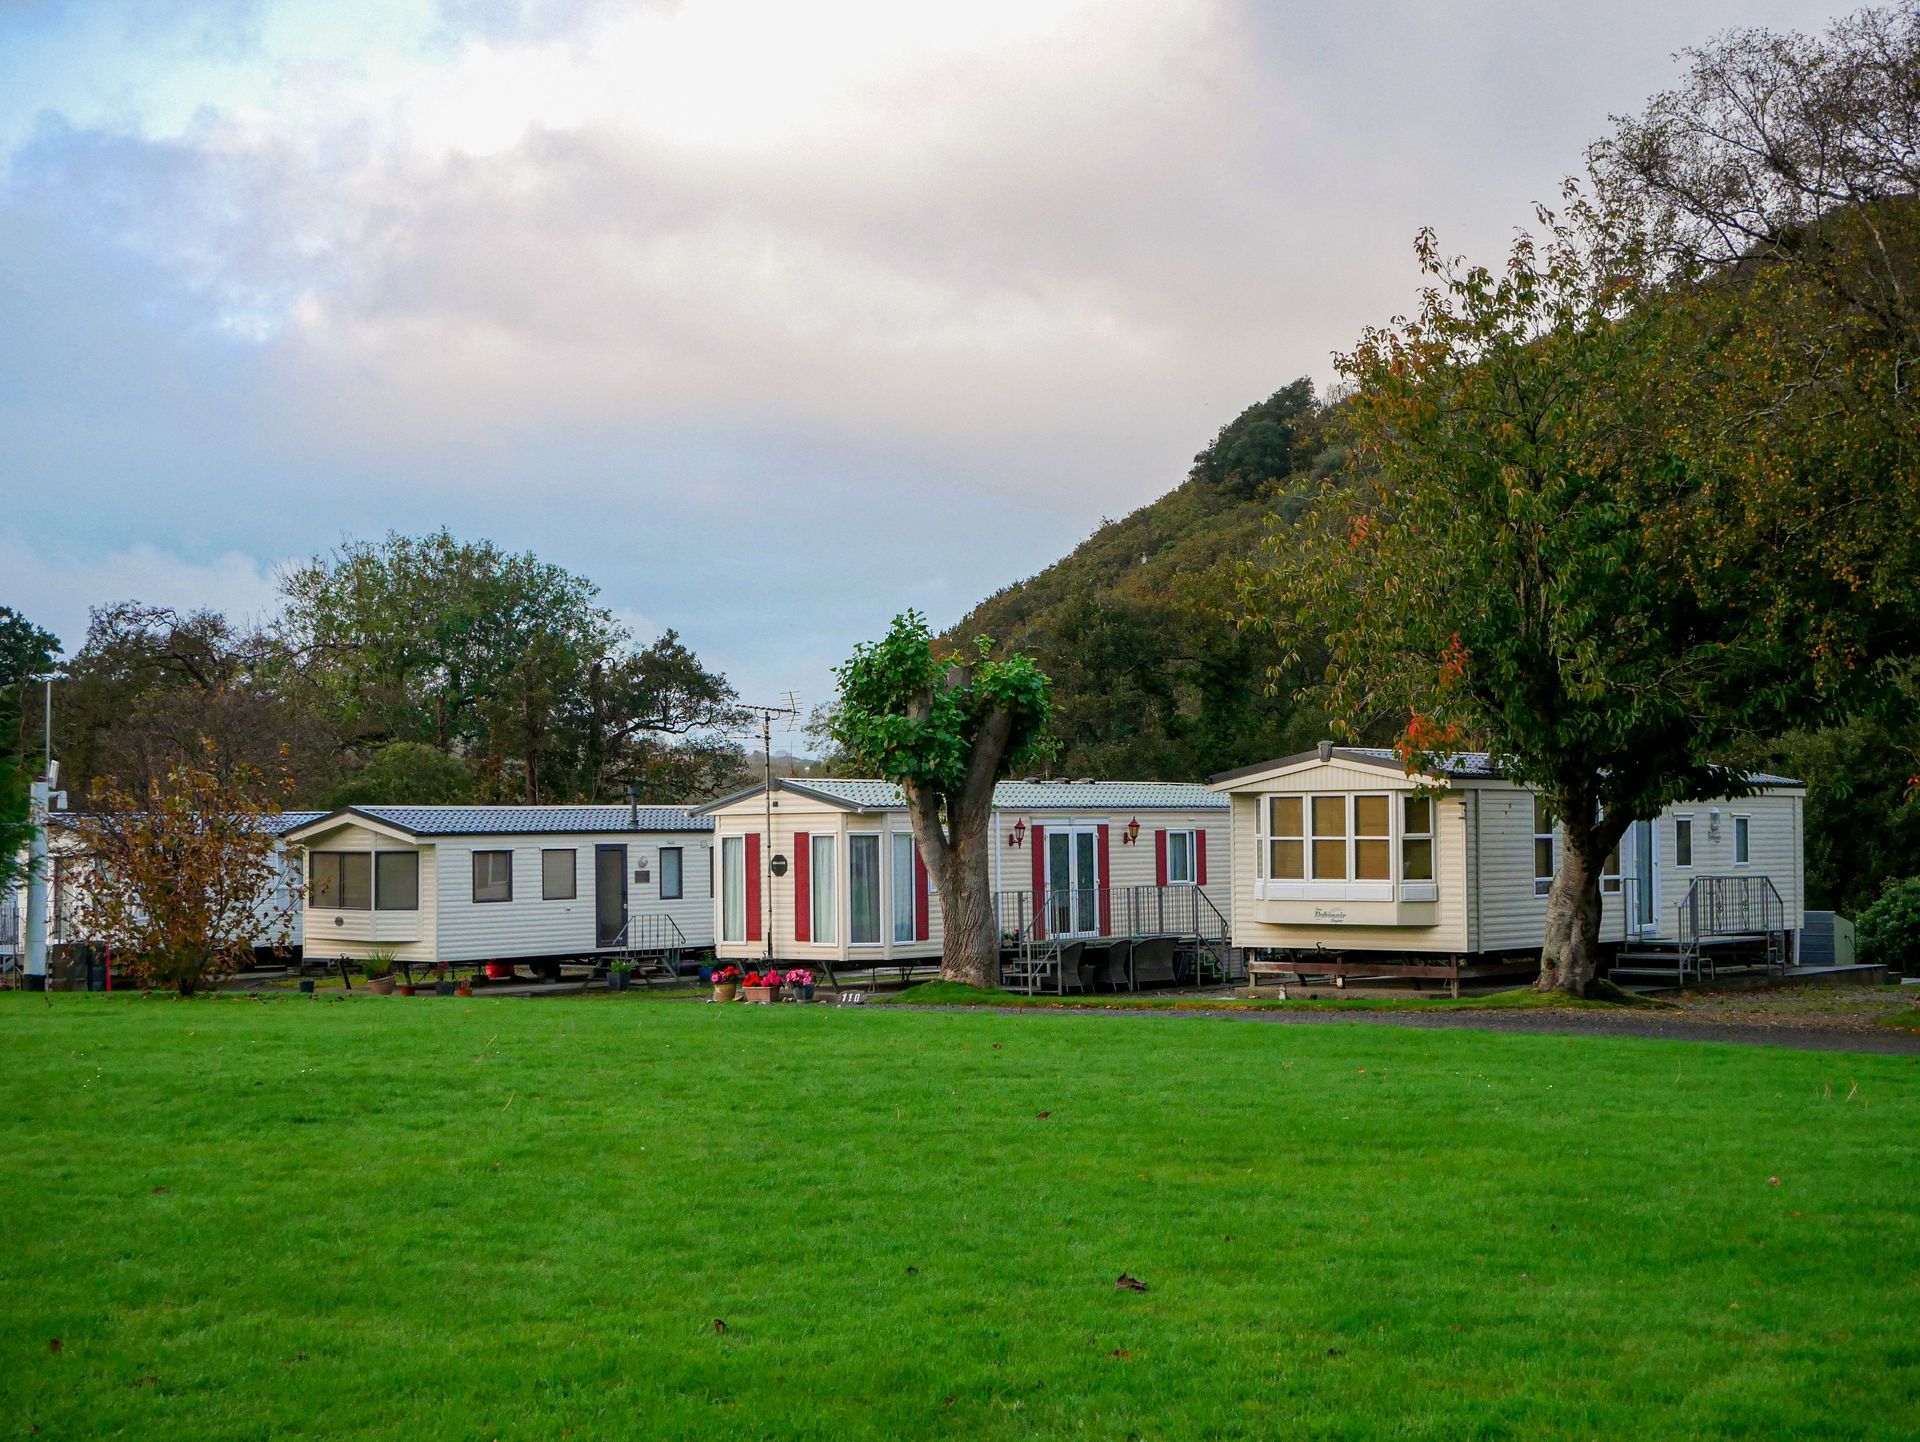
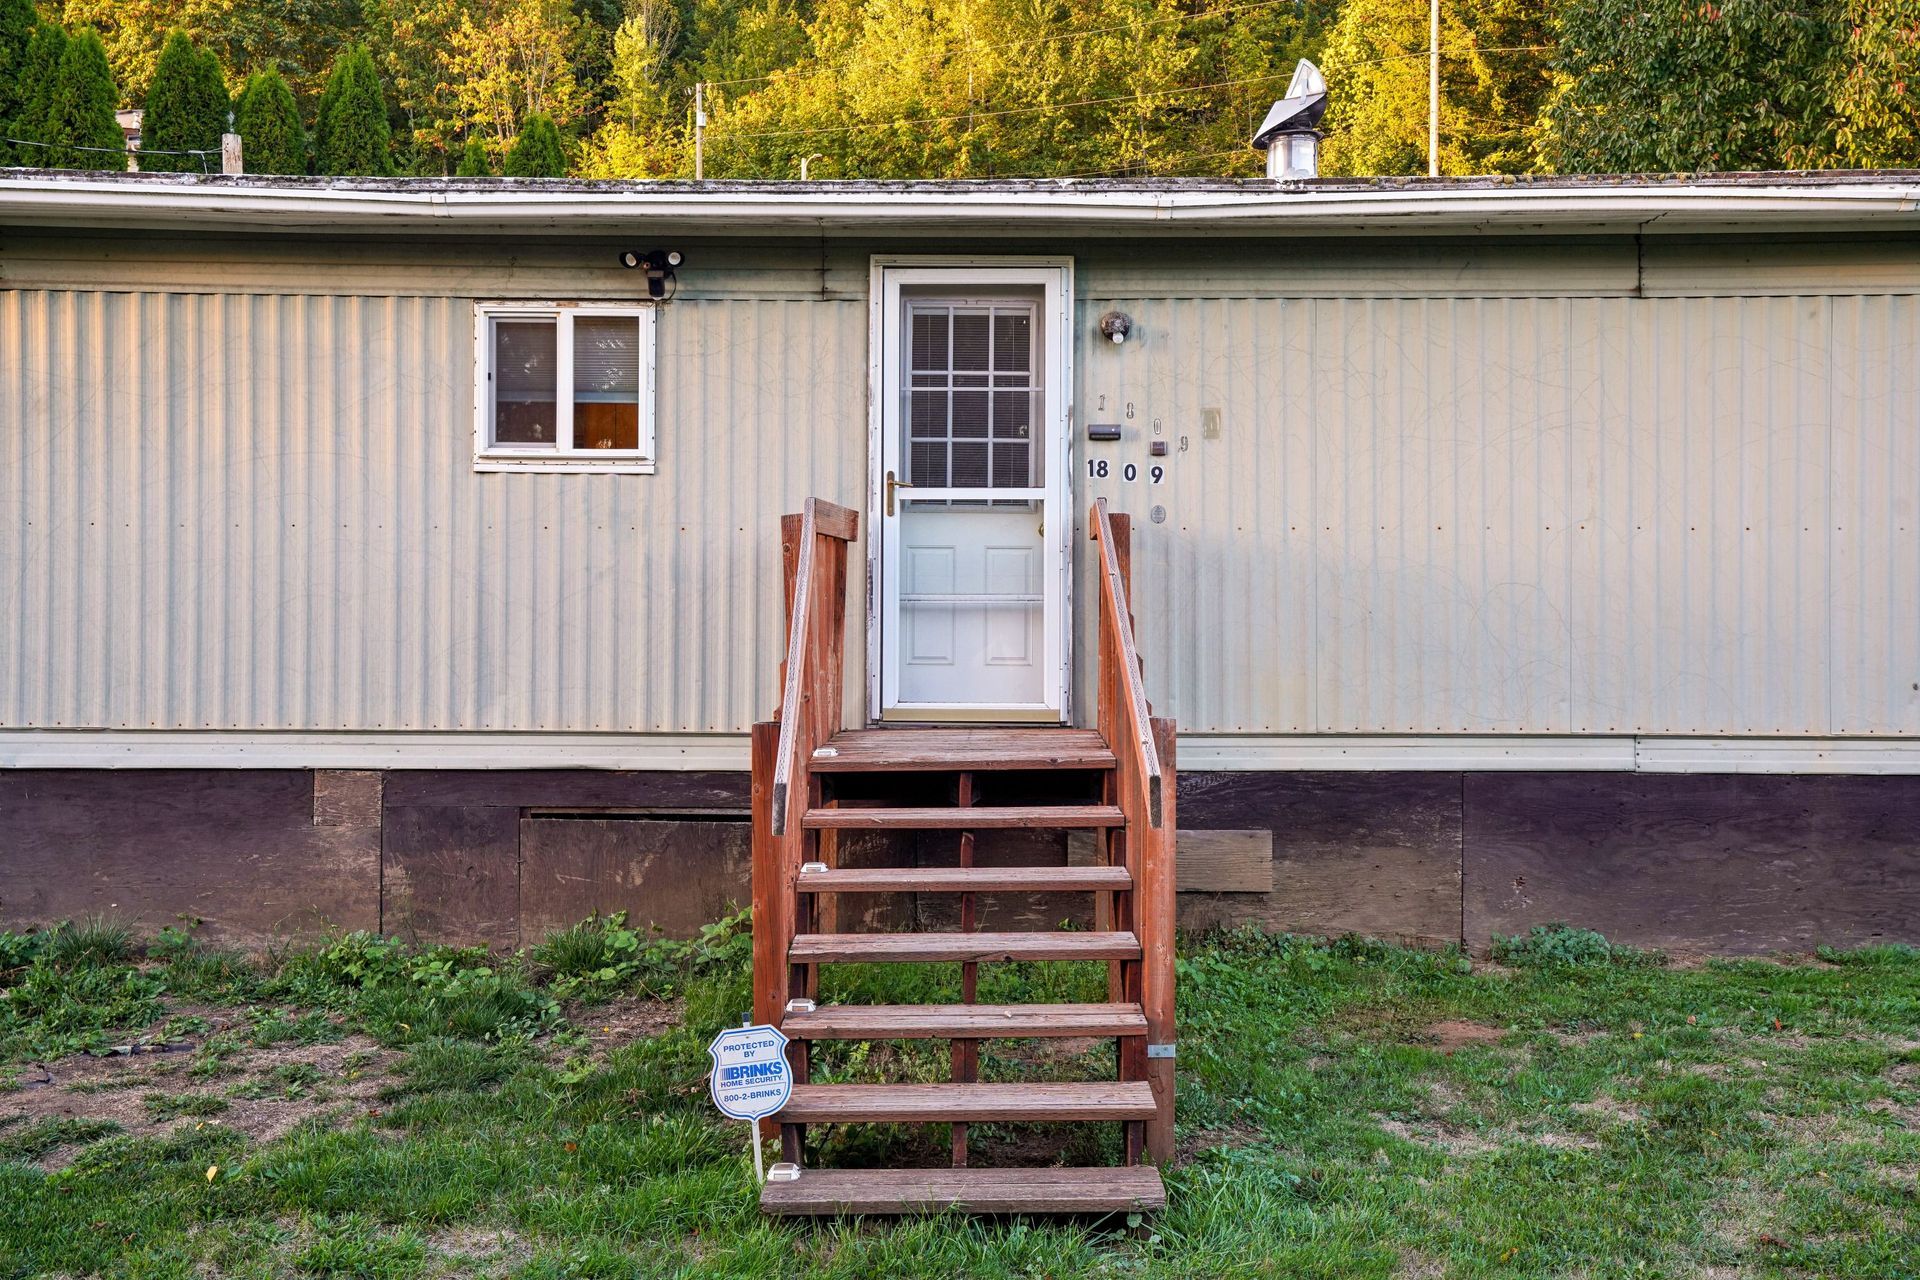
If you own a manufactured or mobile home in Texas, you've probably already run into the wall: you call for a quote, give the year and the make, and the line goes quiet. A lot of carriers simply don't write manufactured housing — and the ones that do often won't touch anything older than a certain year, or anything in a flood-prone or wildfire-prone rural area.
That's frustrating, and it's also exactly the gap we're built to fill. As an independent agency, we carry markets that specialize in manufactured and mobile homes — so instead of one company's "no," you get a real shopping process across carriers that actually want the business.
Here's what you need to know.
Manufactured, modular, mobile — the words matter to a carrier
To you, it's home. To an underwriter, the classification changes the policy and the price:
- A mobile home generally refers to a factory-built home produced before the federal HUD code took effect in June 1976.
- A manufactured home is a factory-built home produced to the HUD code from June 1976 onward, transported to the site on its own chassis.
- A modular home is factory-built in sections but assembled on a permanent foundation to local building codes — it's usually insured much like a site-built house.
The older the home and the more "mobile" its classification, the fewer carriers will write it — which is precisely why the carrier relationships an agent holds matter more here than on a standard brick house.
What a manufactured home policy actually covers
A proper manufactured-home policy (often an HO-7 form, the manufactured-home equivalent of a standard homeowners policy) generally includes:
- Dwelling coverage for the home itself, ideally on a replacement-cost basis rather than actual cash value, so depreciation doesn't gut your claim.
- Other structures — the detached carport, the skirting, the deck, the storage shed.
- Personal property for your belongings inside.
- Loss of use, which pays for somewhere to stay if a covered loss makes the home uninhabitable.
- Personal liability if someone is injured on your property.
Two coverage points deserve special attention in Texas. First, wind and hail — North Texas is one of the most active hail regions in the country, and manufactured homes are particularly vulnerable to roof and skirting damage. Watch the wind/hail deductible closely; many policies carry a separate percentage deductible for it. Second, trip and setup coverage, which protects the home while it's being transported or re-leveled — relevant if you ever move it.
What drives the price
Manufactured-home premiums in Texas move on the factors you'd expect and a few you might not:
- Age and condition of the home, and the roof in particular.
- Tie-downs and anchoring — a properly anchored home is a better risk in wind country.
- Location — distance to a fire station, brush exposure, and whether you're in a flood zone.
- Replacement cost versus actual cash value — replacement-cost coverage costs more up front but pays far more at claim time.
- Owned land versus a leased lot in a community, which changes the liability picture.
Why the independent route wins here
This is the clearest example of why an independent agency beats a single-company quote. A captive agent can only offer their one carrier's appetite — and if that carrier says no to manufactured homes (many do), the conversation is over. We shop your home across carriers that specialize in this market, compare the wind/hail terms that matter most in Texas, and find the one that says yes at a fair price.
If you've been turned down, quoted sky-high, or told your home is "too old," that's usually a sign you were talking to the wrong carrier — not that your home is uninsurable.
Own a manufactured or mobile home in Texas? Let's get it covered the right way. Call (800) 666-2254, text "QUOTE" to (817) 646-6700, or start at tapinsuretx.com — and we'll shop it across the markets that actually want to write it.
Curious how an independent agency stacks up against a single-carrier captive? Read our independent vs. captive agent guide, and if you're weighing your wind/hail deductible, our Texas hail deductible guide breaks down what to expect this storm season.
— TAP Insurance Agency · Call (800) 666-2254 — or text QUOTE to (817) 646-6700 · tapinsuretx.com